Showing posts with label Monthly Budget. Show all posts

Saturday, 30 April 2016

Vacation(s)

With me not working full time and G actually in a unit where he can take his vacation time we have a few trips planned for this year. G had 298 hours of vacation and even after booking the ENTIRE month of September off plus two weeks in June he still has 108 hours left. 

September is our big trip home (Windsor, Ontario) to see our family. G’s never been back since we moved and last time I went was two years ago for a wedding (we could only afford to send one of us). Our plane tickets have been purchases and we spent $229.27 for both of us! Thanks to our credit card perks and points we only had to pay taxes and fees. We were able to take that money from our vacation account savings. The only other major expenses: boarding our dog ($30 a night) and renting a car. Although both our parents have told us we can borrow their vehicles it’ll just be easier to rent a car. G and I are going to be doing our own separate things lots of the time so I could borrow my moms car and G can take the rental or vice versa. Just gives us more options.

The two weeks in June is a late anniversary trip to Edmonton and Jasper. There is a symphony we both really want to see in Edmonton and Jasper is just going to be a mid-week adventure. Last time we went was in Autumn and we had perfect weather so hopefully we are just as lucky.

I’m really looking forward to these trips! I’m happy we’ve made saving for vacations part of our budget even when we don’t have anything planned. That way these ideal trips can become reality without it straining our cashflow or going into debt. We contribute $100 bi-weekly (automatically) but snowball money into that savings account as well. As the numbers become more finalized for our trip in June, I will share our trip budget.

But now I leave you with a super cute photo of Mocha enjoying the beautiful weather!

I wish we could take her to Windsor but I don't know how she would be on a plane :(


- M 

Sunday, 24 April 2016

Balanced Budget

We are absolutely loving G’s new work schedule - so much more flexibility. This week he didn’t even work in the field - he had courses most of the week and has Friday to tomorrow off. He is using that time starting our main bathroom renovation. It’s not a hardcore reno - just a new tub surround (our old one is cracked), new dry wall, toilet, and vanity/sink combo. We are hoping to save the floor but once G starts pulling out the drywall we will see if there’s any water damage. We priced out new vanities cabinets but found out it was cheaper just for G to build our own - so that’s what he has been working on. I think the actually demo will start during his next round of days off. We have the extra full bath downstairs so there isn’t any rush to get it done, I’d rather have it done correctly. 

I did a detailed budget for next month now that I have an idea what our expenses will be. Even with me not working (I didn’t want to include my income since its not guaranteed) our budget still balances - actually with about $350 to spare. That’s a relief! I was worried without my income and double the mortgage payment some things might need to be cut but thankfully not. I was actually thisclose during one of my ‘overthinking episodes’ to changing my TFSA contribution to $100 bi-weekly instead of the $200 we are doing now. I should have just done the budget properly in the first place instead of stressing, lol. 

I calculated what our retirement savings rate is just for curiosity against G’s base salary (which is what I budget with) and we are at 25%! That doesn’t include G’s pension (which is taken off before taxes and automatically so we never miss it). That also doesn’t include any snowballed money we might toss in there during the year. I feel way better seeing that number and a balanced budget. I have been able to work about one shift a week which helps bring in some 'extra' money. I’m sure in the summer with people going on vacation I can pick up a lot more shifts. I’ve been applying to other jobs in the area but no call backs so far. I’m glad we are in a position where being down one income doesn’t hurt our bottom line.

- M

Tuesday, 29 December 2015

Excellent Budgeting Month

Just for the record this is the first year in as long as I can remember that we have gotten passed Christmas without any credit card debt. Even not buying anything dramatic or over the top on Boxing Day - although I did look but more on that in another post. It feels really good not only because I know we are entering 2016 completely consumer debt free but because we could have purchased something if we really wanted too.

We were $141.91 under budget this month and snowballed that money to our vacation fund. The biggest area we saved on was groceries - I had allocated $350 for the month and only spent $256.66. I’m really happy about this because I didn’t feel so great after failing the grocery challenge at the beginning of the month. Other areas under budget: $13 under for fuel and $35.57 under for Mocha.

So with that we moved another $200 to the vacation fund. I figured adding $2000 this month to the moving fund was more than enough and wanted to be a bit selfish. Not all months will be this good - we need to do a city run sometime next month so our grocery bill will be a lot higher unfortunately. You win some, you lose some.


- M

Thursday, 17 December 2015

Bad News/Good News

Tuesday I went to my friends’ acreage right after work. Her dog went missing last Tuesday afternoon and on Friday they found his body in a trap about a mile from their property. Friday morning another one of their dogs came limping back to the house, lip completely mangled, blood all over her face, eyes blood shot. My friend took that dog to the vet right away and her husband went into the bush with his gun (thinking it was coyotes). After about 10 minutes walking thru he found the other dogs’ body in a noose like trap. They didn’t know anyone was trapping near-by. The Conservation Officers for the area are involved – as they know who’s traps they were and its not his first time doing it illegally/without care. Her other dog somehow survived the trap that caught her but she is still recovering – what a fighter. So after work on Tuesday I picked up a flower arrangement I ordered into town and went to spend the evening with her. We had dinner, talked about what happened: she’s more at peace now knowing where he is and what happened to him. They buried him near a lilac bush where he would always bed– a very fitting final resting place. I left there after a few hours of visiting, drove back to town and gave Mocha a big hug when I got home.

On Wednesday I got a Christmas card from my grandparents with a $160 cheque. I deposited right away, then G & I agreed to move it over to our vacation account to help fund our trip back home to Ontario next year. Instead of $160 I moved over $200 just to squeeze our budget a bit. The account is sitting at just a little over $800.

Today, the good mail continued but this time it was our Energy bill (surprise, surprise). We are on an equalized payment plan with both our Power and Energy bills. Our Energy bill for the last year was $160/month. But they reassessed for 2016 and our monthly bill is going down to $115/month AND we have enough credit that we won’t have to pay our bill again until April – score! Now, we are used to the $160 in our budget and I don’t intend to start spending it on crap, so what’s the plan? From January until April I’ll snowflake $200 into the moving account (rounding up to once again squeeze the budget and I like round numbers better). That’s $600 extra dollars added to the account in the next three months. Then following months until we move I have a snowflake of $50 to help fund our moving expenses.

- M


PS: Any pet owners reading; hug your animals tight & maybe an extra treat <3

Saturday, 4 April 2015

2015 1st Quarter Spending Review

(That title makes it sounds like we run some sort of business lol).

            Wow, first quarter of the year gone already. This year has been pretty awesome for us: emergency fund fully funded, consumer/vacation debt paid off, started focusing on our car loan, and I got a new job with a pay increase. All this motivation really comes down to us keeping a spending analysis every month. I enjoy being able to see, visually, where all our money is going and it keeps us aware of how we are doing as the month goes along.

            Last year I posted this pie chart every month, but this year I have decided to only post four times. Our spending doesn’t differ much month to month and if anything did come up, I would normally write a post about it.

            We adjusted some of the categories slightly; getting rid of the ‘Savings’ category and adding a ‘Travel’ slice. The old Savings category had all our planned spending account (i.e. Travel Fund, Personal spending money), so we decided to just have the travel fund be it’s own category and lump our personal spending money into the Personal category – which makes a lot more sense!


Home (9%)

Most of this is just mortgage and insurance payments. The weather has been getting nicer here and we have started some of the project we have been waiting to work on all winter. Last weekend we painted the living room and G purchased the lumber for a desk and photo shelf he will be making for the house. We invested in beautiful quality lumber that I don’t mind spending the money on, as it will be a handcrafted piece that G & I both designed. Very excited for the end result!

Utilities (7%)

We are on equalized payments for our gas and energy so this category should stay consistent. We did get a notice with our water bill that the town has increased some of the costs (effective in June) but they aren’t significant enough and I don’t mind investing into the community.

Transportation (15%)

We are averaging around $75 a month in gas, this is mainly because of me walking to work everyday and G taking the cruiser home during a stretch of days he’s working. The reason this is such a large percentage is because of all the extra payments we have been making to our car loan. This is one category I’m hoping will increase as the year goes on as paying off our car loan is the main priority. We have exactly $15,000 left and are currently on track to have it paid off for the end of the year.

Debt Repayment (15%)

We officially paid off the last of our vacation spending in February thanks to our Income Tax refund. The plan for the rest of the year is not to carry any consumer debt at all so this slice should slowly disappear as the year goes on and the other categories (like transportation) take it's place in our cash flow. We do use our credit cards for pretty much all our purchases but we use them responsibly: something I was never able to do before.

Long Term Savings (22%)

I love that this is our biggest category! A nice chunk of this is (again) thanks to our tax refund that allowed me to add $2000 to my TFSA. Also we doubled the current contributions to my RRSP by purchasing some funds at Tangerine.

You want to know know something else that’s pretty neat? I have officially crossed the $10,000 milestone in my own personal retirement accounts!!! :D It was only 4 months ago (December 7th) that I was so excited to post about hitting $5000 in the accounts. Although, there won’t be any super sized snowflakes for a while I want to increase my goal and have at least $20,000 in my accounts by the end of the year (up from $15,000).

We should be getting G’s pension report soon-ish so I’ll be nice to have a complete dollar figure of how much we have actually saved between the both of us. We do not include his pension contributions into our budget as it just comes off automatically but it’s nice to know he is paying into an awesome plan that we are extremely lucky to have. I think once we get that report I will do a NetWorth statement, my first ever!

Food (9%)

This is still an area I struggle with. I’m averaging out at around $565 each month but that’s off from my goal of $500 each month. We did have one huge Costco run in February that bumped up our costs but I’m okay with that because we still haven’t really made a dent in the meat we were able to stock up on. I’ve been on track and motivate in the kitchen, trying about two new recipes a week. Most of them have been simple but delicious. My friends laugh at me because I prep all the ingredients before I start cooking and have everything lined up and ready to go like I’m on a cooking show but with each awesome meal I make my confidence is growing! J  

Shopping (9%)

January was a spending month for us. We were able to snag a lot of good deals after the holidays until a rifle my husband had been eyeing for nearly an entire year. Also I made an order from IKEA to help finish off the living room now that it’s painted. We have still yet to receive it but it was ordered and paid for in March. I got a rug, wire holders to install under the new desk, some photo frames and a few more decorative pieces. We don’t have an IKEA in Saskatchewan at all so I was very excited to learn that I had the option of ordering online!

Travel (4%)

No, we didn’t go anywhere to escape the cold winter… This is just our Travel fund. The first two months of the year we were only able to put about $200 each month but March we put $600. Budgeted from now on we will be contributing at least $500 each month. We do have one small anniversary trip coming up in May but this fund will not be touched for that.

Personal (10%)

Medical is our biggest expense in this category but not really because we are waiting to get reimbursed for some massages. As per my explanation, both G and I have our spending accounts show up here. G’s will be increasing a bit once his raise finally goes thru, if it ever shows up (yes we are STILL waiting)

--------------------------------------------------------------------

I hope everyone has a good Easter!

- M  

Sunday, 30 November 2014

November Budget Overview


Home (12%)

Regular mortgage payments and insurance. Abnormally, this month we purchased some new pots and pans from Canadian Tire that were on awesome clearance. We have a cheaper set that was given to us as a wedding present that definitely were still useable but I always kept my eyes peeled if a nice set ever came on sale. The set we found was an older style that wasn't being made anymore and the box was a little beat up but the lids and pans themselves were beautiful! I've forgotten how nice it is to have water come to a boil so quickly.

Utilities (5%)

Normal range for us but I expect our energy bill will be going up next month. Today was -40C with the windchill, our poor little furnace: its not even officially December yet!

Transportation (9%)

We had a few trips this month for various reasons, including our dog getting sick and having to drive to the vet a few times. I'm hoping next month will be better in this category.

Debt Repayment (16%)

Line of credit payment, down to an even $4000 owing.

Long Term Savings (20%)

All our automatic transfers to different investments. We will find out wither we get a bonus this month or not at my work and if I do any money will go into my TFSA. I'm hoping to add another $500 or so this month to give it one final boost before the end of the year, so hopefully this percentage will be higher next month to reflex that.

Food (10%)

I really need to find a way to cut this back.

Shopping (5%)

A friend of mine had a Scentsy party so I purchased some new winter scents and other little things during the month we picked up, like a star for our Christmas tree!

Savings (9%)

Money into our house and vacation fund. Currently on track for our Yukon trip :)

Personal (14%)

I don't think I've seen this number that high before. A large portion of this number is vet visits, but we always have a bit of Christmas gifts, cards, etc thrown in there as well.

---------------------------------------------------------------------------

I'm glad this month is done. Not the best in my opinion and I'm kind of getting bummed out. G didn't get any overtime at all even though the payout keeps creeping up - it's extremely annoying. But I'm hoping next month the debt repayment percentage will be a lot larger. I just want to LOC gone (again)...

- M

Saturday, 1 November 2014

I'm back! October Budget Overview


Why hello everyone! I'm extremely sorry for disappearing so suddenly but it was a busy summer and fall as well. I believe things should be returning back to normal, hopefully. Winter has arrived here (hence the slow down in activities). Yesterday afterwork I walked around town with a friend from work as her son was trick or treating. In -6*C weather, we were all freezing after 2 hours. I've never walked home so fast in my life! Jumped straight into bed and tried to warm up haha

Soooooo, I'm really hoping that you would be wowed by our Long Term Savings pie slice but you may be wondering why we have a slightly larger pie slice that has returned. Debt Repayment. Yup :(  I'm kind of embarrassed but not at the same time. End of September G & I finally went on our honey moon. After nearly 2 ½ years of marriage! We took a road trip to Alberta (Jasper & Banff area) and we had an amazing time. That is a trip I'm going to remember for the rest of my life. I've never seen the mountains before and we soaked up every single second we could, went on so many hikes and a lot of activities. I don't regret a thing. Well that's a lie, because I wish we would have planned better but I'm learning! I have our next trip (Whitehorse, Yukon) planned out, priced out & a savings plan in place. So our Line of Credit is sitting at an even $5000 at the moment and the plan is to have that gone by January, while still keeping our Long Term Savings as it is (since all of that is automatic).

Good news money wise is that I have increased my TFSA contributions. So we are now putting in $200 bi-weekly. G celebrated his 2 year anniversary in his career which comes with a bit of a pay bump. I also got a pay increase at the end of summer. And the company I work for just finished their fiscal year so this means bonuses and another wage increase (hopefully) -- although I don't find out until next month. Oh! And I finished all my Christmas shopping.  :)

I'm sorry this post is so all over the place! But it feels good to be back and I promise less chaotic posts next time.

- M

Tuesday, 1 July 2014

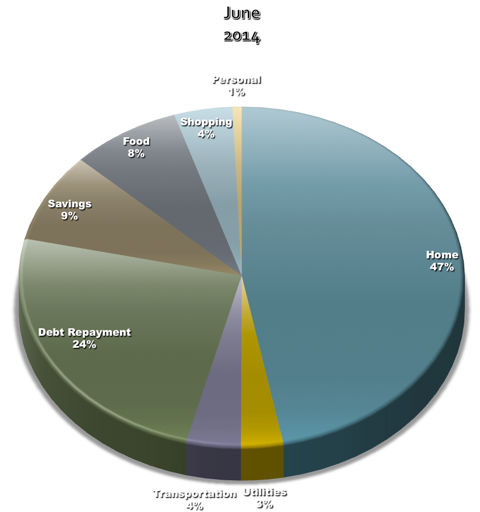
June Budget Overview


Happy Canada Day! I'm enjoying my day off by doing laundry and cleaning my floors. Then maybe venture outside and see how many weeds I need to pull out of my garden, that's just a maybe though ;)

Debt Repayment: (24%)

I hope this is the last time I ever have to talk about this category again! G & I kicked our Line of Credits ass this month. I explained our payment breakdown in detail in my last post so I won't explain it here. It's done!! :D

Savings: (9%)

Our savings this month was a lot lower then we normally try to save, and it should be even lower since we completely drained our emergency fund, but I'm not sure how to show that in my budget since everything goes thru our chequing account. Oh well, next month this number is going to be a lot higher as we focus on replenishing our EF.

Food: (8%)

We spent A LOT on food this month. Over $1000.00 for just two people... that is embarrassing to write. BBQ meat is the killer of our budget though and we entertained a few times this month for some of G's co-workers (and those drop in's are usually unexpected and G ends up going to the store to get some BBQ stuff because it's the easiest). Ugh and my plan of eating what we had fell to the waist side but I still have the sheet of meal plans so I hope to draw from that a lot in July.

Shopping: (4%)

Mostly home stuff; like a new wireless router, some tools G wanted that were on sale, some nail polish for myself (not home stuff lol). 

Personal: (1%)

Only thing that was personal this month was my father's day gift! At only 1% it looks like I actually didn't get him much but my mom says he wears the safari sun hat I got him nearly everyday :) It'll be perfect for him to use during their summer vacation as well since they both do a lot of hiking.

Home: (47%)

That GIANT pie slice is what a new roof looks like ladies and gentlemen. Another major factor in clearing out our emergency fund but it was completely paid for in cash (well, cheque actually) and it could not have been completed at a better time as we've had a ton of rain here this month! Oh the joys and responsibilities of home ownership :P

Utilities: (3%)

Normal, aka boring 

Transportation: (4%)

I transfered to an office here in town at the end of last month so I'm not commuting 1 hour a day round trip, 5 days a week to get to work. It takes me 5 mins to walk to work or under a minute in the car for the days we had some really bad weather. We only filled up the car once this month, rather then once a week. This number is just car payments, insurance and the bit of gas. 


---------------------------------------------------------------------------

This month started off really down for me but ended on the huge high note of finally paying off our LOC. I'm not going to lie: I'm actually kind of nervous about slipping into old habits when it comes to our spending because we don't have our debt payment being our main focus. Since we've both turned 18 and had credit cards, G & I always had consumer debt. Getting into that shift of re-adjusting to savings is somewhat terrifying. We've both talked about this a lot on weekend and we opened 2 savings accounts: one for my personal spending and one for G's personal spending. Each paycheque he gets we set it up so $100 automatically gets send to his account and same with my paycheques, $100 into my account. G & I both realized we need limits when it comes to our spending and this way we each have our own spending accounts. We also promised not to judge each other's purchases either, that way I don't have to complain about how expensive video games are and I don't have to hear him nag about how much stuff at Sephora is. :) I think this is going to be excellent not only for our budget but for our marriage as well! :P

- M

PS: I don't want to get all sappy but I really want to say thank you for everyone who has their own personal finance blog. I honestly do not think I would be in the position I am today with my finances if it was not for reading other peoples post. They are constant inspiration and always motivate me. I'm really glad I found this community when I did :) Thank you!

Sunday, 1 June 2014

May Budget Overview


Look at that beautiful debt repayment slice... I could stare at it all day.

Debt Repayment: (48%)

We are winding down everyone! Our LOC stands at just $3500. This month we put just a tad bit over $5,500, which is actually $500 short of our goal. I'm kind of kicking myself because I could have definitely done another $500 if we didn't go on our city trip but oh well. $4000 of that payment came directly from my income tax refund (such a good feeling to transfer that amount) and the rest came from regular payments. Our goal this month is to put $2000. G has been working a lot of overtime the last week, and they are going into the busy months short by two members so I suspect a lot of overtime this summer for him as well. The money is really good but I hope he doesn't get burnt out: I will definitely be watching for that.

Savings: (12%)

We have all our savings automatically transferred from our accounts the day our pay cheques go in so we don't even miss it/ notice it's gone. It's the best way to do it in my opinion! Once our LOC is paid off we plan on bumping up savings quite a bit and I'm hoping to have a more specific visual break down on what we are actually saving for (i.e. Retirement, Car, House Repair, Emergency, Vacation, etc.)

Food: (8%)

Booooo. We spent just a little bit under $900 on food this month. Not happy with this at all. $200 of that is from restaurants alone. Most of this number is from our out city trip to Humboldt where we stocked up on a lot of grocery and then of course ate at restaurants. I am happy to report that I saved a total of $69.48 this month strictly by clipping coupons, and I also saved a bunch shopping sales but I haven't calculated that yet. Hoping to stay at a reasonable amount for June, we have a lot of frozen meat to use for the BBQ.

Shopping: (6%)

Purchased a few items of clothing during Victoria day sales online, G pre-order a video game a while back and the PayPal transaction went thru when the game shipped and when I was in Humboldt a did a bit of drug store shopping -- the majority of it being shampoo, conditioner and medicine but I included it here.

Personal: (4%)

I'm actually surprised how low this number is considering this includes a Mother's Day gift, anniversary flowers G bought for me, and the dental cheque I wrote (which I will get reimbursed for anyways). 

Home: 13%

Besides are our mortgage and insurance payments this number is a lot bigger this month because we purchased some bushes & flowers for our front yard and G purchased a few tools he had been waiting to go on sale. Next month this number will be huge because we are going to be getting the bill for our roof, not looking forward to writing that cheque lol

Utilities: (3%)

Normal, aka boring

Transportation: 6%

I'm so excited to see what this will be next month! Now that I've started my new job here in town, I'm not doing the hour round trip commute 5 times a week. Instead, I know walk to work and walk home for lunch aswell! Only time I really see myself using the car is if it's thunder storming, but I doubt that will happen often. 


---------------------------------------------------------------------------

Although it looks like we've had an excellent month, I'm kind of disappointed. $500 short of our debt repayment goal, food spending way over, shopping for the clothes on Victoria Day. Wow, I'm actually really embarrassed with myself how we let some of our spending get so out of control. Here's hoping next month is better. We are so close to paying of the LOC, I think that's why it's hitting me the hardest. I just want it gone! :( But there's no one to blame but myself.

- M

Saturday, 3 May 2014

April Budget Overview

Hi there everyone. It's time to bust out my beautiful budget pie chart and review!

Debt Repayment: (41%)

We were able to put just a tiny bit over $4000 towards our line of credit this money. The majority of this payment being from G's (husbands intial) income tax and a reassessment we had done (which I talk about in length two posts ago). We are finally down to four digit numbers, people! We ended this money with a closing balance of exactly $9000 left owing :o)  This month our goal is to put $6000 in total, broken down as: $4000 for my income tax return & $2000 for regular payments. It's definitely do-able; and if we can put more we will. I'm really excited and determined! We are so close

Savings: (15%)

We have all our savings automatically transferred from our accounts the day our pay cheques go in so it's nice to know we were able to save $1500 this month without really missing it. We have G's TFSA, my TFSA, my spousal RRSP & our Emergency Fund. The amounts in our TFSA's and my RRSP are pretty small right now but we have to start somewhere right?

Food: (8%)

This number would have been lower but G brought home Boston Pizza twice this month from when he had to go to PA and Yorkton for work; and one does not simply say no to Boston Pizza. This number might be a bit higher this month as we have visitors coming to stay with us at the end of the month and we have our marriage anniversary coming up soon so we might treat ourselves a bit. Though there's not that much choice here in town (there's 2 restaurants) so it's not anything fancy lol.

Shopping: (8%)

Most of this was my clothes shopping binge. You know what though? I wore those skirts this week to work and I felt like a million bucks ;o)

Personal: (5%)

This number includes paying our accountant for doing our taxes so it was a bit higher because of that.

Home: (10%)

No home repairs done this month; so it was just mortgage, insurance, etc.

Utilities: (6%)

Normal, pretty boring.

Transportation: (7%)

Car payments, insurance and gas

---------------------------------------------------------------------------

Pretty good month in my eyes! Seeing how big the debt repayment pie slice is makes my mouth water (bad pun). G and I were talking a few days ago about what our plan is going to be once the LOC is paid off and how we are going to reallocate that money. We both agreed we are living really comfortably and not feeling like we are missing out. We plan on saving for a truck so I think that's going to be a new priority for some of the money, then maybe ramping up our TFSA's contributions (we are a long way from maxing them out), and the rest for planned spending? It would be nice to have our car paid off too, and the house, and re do the bathroom upstairs, etc etc etc. The list will never end will it?

-M

Sunday, 2 March 2014

February Budget Overview


            Happy March everyone! Too bad here in Saskatchewan it’s -40C, so much for spring, eh? Today’s post is going to be a complete overview of our February budget. This was the first month were we really were meticulous about tracking where our money was going and hubby made it all into a neat pie graph.


(She's real pretty isn't she?)

Debt Repayment: (43%)

We worked our butts off this month and were able to put nearly $3000 towards our debt. Hubby got his raise that was due back in October so one of his pay cheques was a lot more then usual. My goal is to definitely keep this number up above $2000 in the coming months.

Savings: (9%)

$400 went to our Emergency Fund and yesterday we hit our first goal of having $5000! This number will also be a bit higher next month as we have an appointment to discuss RRSP with our financial advisor. This is the first time investing so we are both really excited and nervous to loose our investing virginity! Lol Wish us luck!

Food: (8%)

A bit higher then usual as we went to the city to stock up on a few things that are more difficult to get in our small town – and my husband did a few shops on his own this month so that kind of messed up my usually extremely planned out shopping trips. He’s getting much better though about purchasing things that are on sale! One thing at a time I suppose.

Shopping: (10%)

Again this number was a lot higher then usually due too the city trip. My goal is to have it under $200.00 next month.

Personal: (3%)

$100 of this was birthday gifts for a few friends of ours; the other $80 was for things like Netflix’s, two eBooks I purchased, a prescription and hubby purchased a video game expansion. There isn’t too much to do in a small town so this number is always pretty low.

Home: (12%)

Mortgage payment, insurance, and all that really fun stuff! It’ll be a bit more next month as we have a plan to paint our main floor bathroom, but those are all the home improvements we have planned next month, as it’s just too cold to do anything else!

Utilities: (6%)

Boooooring. This number might be a tiny bit higher next month, as I believe our water bill (which comes every 3 months) will be due.

Transportation: (9%)

$360 of this number went to car payments; the rest was fuel and insurance.


To sum up February, I think we did pretty well. Our biggest accomplishment was paying off all our credit cards and still being able to put $2000 on the LOC. That was a really exciting day for us, lol. There is definitely room for improvement and our trip to the city kind of threw us off bit, but that’s why I’m tracking this: to see where we can improve and were we are doing really well. :) I really love being able to see where our money is going. It makes me excited to see with Debt Repayment being such a large percentage what we will be able to accomplish once that debt it gone! Hopefully those days aren’t too far away…